All Categories
Featured

How Retired Adults Prepare for 2026 Medical Costs
Table of Contents
We're sorry, but we were unable to authorize your demand. Please call us at 800-433-9196 and offer recommendation number SWAF-18. d31c2117.1789333798.3 d6b4154. We excuse any trouble. 0915-82LR
Retirement Planning Huntington BeachMuch like how cereal can be a part of a balanced breakfast, life insurance coverage can be part of a balanced and holistic retirement planning technique; nevertheless, the first obstacle to conquer when thinking about whether life insurance can be leveraged in your customers' planning is the general public's subsiding understanding on the topic.
1Public perceptions on life insurance coverage are frequently at odds with reality, particularly among younger generations: just 36% of Gen Z individuals own life insurance, with rates normally increasing by age regardless of the energy of policies at any stage of life and the reality that such a space leaves younger Americans uniquely susceptible to life's uncertainties.
How Retired Adults Prepare for 2026 Medical Costs
Should life insurance be one of those options? On paper, life insurance coverage is frequently simplistically comprehended as a death benefit: one or more individuals receiving compensation in the type of money upon the passing of another individual to pay for expenditures, supplement enduring loved ones, and other needs.
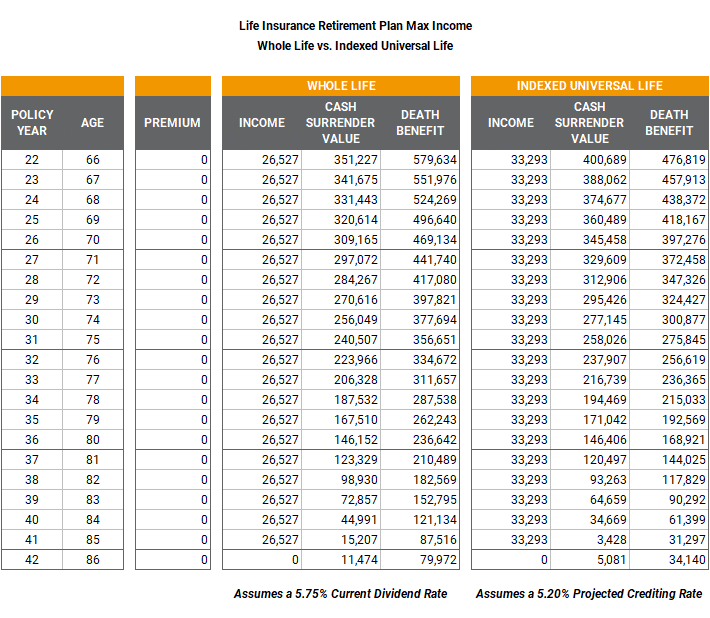
Much of this technique has to do with leveraging cash worth life insurance: a type of life insurance coverage that policy holders pay money into gradually to construct worth, much like a 401(k) or individual retirement account and which they can later make withdrawals from largely tax-free. Such policies often have greater premiums for holders, and it's true that securing too much cash can eventually diminish survivor benefit, however professionals state with appropriate management, customers really can have their cake and consume it, too.
"In some methods, these policies can do not simply double task, however triple task for the retired person. If using a money value policy with a long-lasting care (LTC) or chronic illness rider, that agreement can provide tax-free retirement earnings for the healthy senior citizen, be a source of necessary earnings for the retired person who incurs a long-term care occasion, and still eventually pay a tax-free survivor benefit to successors."Paul Wetmore, MBA, LUTCF, CLU, FSCP, an adjunct professor of insurance coverage at The College, accepted Parrish that using life insurance coverage can really reduce pressure on a customer's other retirement planning possessions and allow them to perform much better with time."For instance, a customer without the hybrid life/LTC policy may require to have actually more assets allocated for an unanticipated requirement and be needed to keep them set aside in something underperforming maybe not in money, but something low-risk and extremely liquid," he said.
Preparing for Rising LTC Costs
In reality, there's even a term for it: Life Insurance Coverage Retirement Strategy, or LIRP for short. Regardless of popular understanding, it's often good to motivate customers to buy life insurance young so they can continue to pay into it as they age. That said, even with clients already in retirement, life insurance coverage can still be a valuable financial investment.
"In the second, tax-free life insurance coverage is far more efficient as a tradition automobile than leaving IRAs, 401(k)s, and other taxable accounts. Also, cash worth life insurance can be a beneficial tool for securing a tax-favored source of retirement income that can help supplement other sources of retirement income and bridge Social Security."Wetmore agreed, but also keeps in mind that life insurance coverage services might still differ subtly depending on the economic status of the client."Very rich clients may be more focused on strategic earnings tax-planning strategies rather than the long-lasting care benefits, as numerous high net worth customers are prepared to money their likely healthcare from their possessions rather of LTC insurance," he stated.
"Remember that most likely than not, the retiree's kids will be inheriting their moms and dads' wealth when the kids remain in their peak making years and potentially in a high tax bracket. Also, research study has revealed that when retirees leave a known tradition instead of simply leaving whatever is left over, they are better in retirement.
Economic Impact of Longevity for Seniors
1 Nerdwallet - Is Whole Life Insurance a Good Financial Investment in 2026? Updated December 17, 2025. . Accessed January 26, 2026. 2 Nerdwallet - What Is the Life Insurance Death Benefit? Upgraded June 25, 2025. . Accessed January 26, 2026. 3 USNews - What Is a Life Insurance Retirement Plan (LIRP)? Updated October 24, 2025.

Latest Posts
Holistic Retirement Strategies for 2026

Preparing for 2026 LTC Costs
Understanding Variable Annuity Options for Senior Security