All Categories
Featured

Financial Impact of Increased Life Expectancy for Seniors
Table of Contents
When this happens, the insurer pays you dividends or interest, so the cash in the policy grows as a sort of financial investment. When you do retire, you can begin taking cash out of the policy in the type of a loan to yourself. You can keep taking money out of the policy as long as you want, whenever you need it, and it is simply a loan to yourself. The only limit on just how much you can secure of the cash balance is the amount of the policy. When you ultimately die, your $1.5 million will settle this.
$1.2 million loan and leave your heirs about$ 300,000 in money. The cash entered into the policy, it was never taxed as it grew, and after that you took it out without paying any taxes, since it was a simply a loan. It appears too great to be true, however it is in fact all true and possible. This unique life insurance coverage policy does not come inexpensive.
If you miss out on one of these premium payments, you might lose the insurance policy and possibly lose some of the money you have built up in the policy. Third, the interest and dividends paid on your money in the policy are typically low compared with what you might earn in other places. A life insurance policy can help change the income that your enjoyed ones are counting on you to supply.
Retirement Planning Ontario CAAnd, a life insurance policy can settle financial obligation, your funeral expenses, and future education expenses for your kid. After those things take place, you probably don't need life insurance. Since with these threats it is possible to figure out about how many years your life needs to be guaranteed, it generally makes more sense to buy lower-cost term life insurance coverage for just the variety of years (the term)that you need it.
Planning for Future LTC Fees in the US
Many people do not contribute the maximum amount the law permits them to contribute to their 401 (k) or IRA retirement accounts. These are normally the first and best choice for retirement cost savings for a lot of people. If you have a fee-only monetary advisor and investment manager, they will help you put this new idea in the context of your overall monetary life.
In this post I'm going to review Tax-free Retirement Preparation with Life Insurance Coverage. These are also understood as Life Insurance Retirement Plans.
It is a crucial topic to keep in the rotation and come at it from multiple angles. I have two objectives for this post. The first is that I desire to reveal you how a life insurance coverage policy can produce 2 to 3 times the income from the very same amount in other kinds of cost savings. Let's start with this: 2 to 3 times what? Financial Advisors use The 4-Percent Rule as a Rule-of-thumb for figuring out the safe withdrawal rate from retirement cost savings.
You wish to take as much in income as you can, but you don't desire to lack cash while you are alive. Go out and do a search on"The 4% Guideline". The agreement nowadays is that 4%is too high. You ought to recognize that this implies that a person with$ 1 Million in a 401(k )can securely take $40,000 per year in distributions for as long as they live. If this individual is in a 25 %tax bracket, they will lose $10,000 to income taxes leaving them with only$30,000 of annual earnings for every $1 Million in retirement savings. Even even worse, if tax rates are greater, such as 40%, they will only net$24,000 after tax! If you look carefully at a properly-designed, optimal over-funded policy illustration, you will discover that the ratio of income to the previous year's cash value is more like 8%. Have a look at this footnote for caveats and assumptions.What this suggests is that someone with $1 Million in cash value at retirement age might securely take $80,000 per year in TAX-FREE Earnings. It should be apparent that $80,000 has to do with 3 times the after-tax earnings of what our theoretical$1 Million 401(k )can produce depending upon the tax rate. Now I want to discuss to you HOW this is possible. This is what every pundit gets wrong.
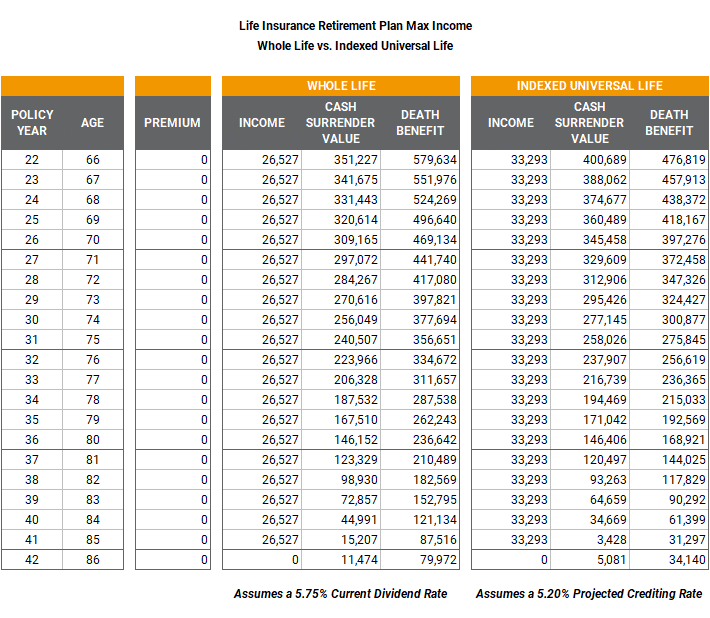
They just do not understand how to convert money worth into"earnings ". The"so-called"specialists just compare accumulation. If a tech mutual fund is growing at 10%per year, you are going to wind up with a lot more cash by the time you reach retirement age.
Economic Challenges of Longevity for Seniors
If this individual is in a 25 %tax bracket, they will lose $10,000 to income taxes leaving them with just$30,000 of yearly earnings for every $1 Million in retirement savings. If you look carefully at a properly-designed, maximum over-funded policy illustration, you will discover that the ratio of earnings to the previous year's cash worth is more like 8%. Take an appearance at this footnote for caveats and assumptions.What this suggests is that someone with $1 Million in money value at retirement age could securely take $80,000 per year in TAX-FREE Earnings.
They just do not understand how to transform money value into"income ". The"so-called"experts merely compare accumulation. If a tech shared fund is growing at 10%per year, you are going to wind up with a lot more cash by the time you reach retirement age.

Latest Posts
Holistic Retirement Strategies for 2026

Preparing for 2026 LTC Costs
Understanding Variable Annuity Options for Senior Security